
How to find off-market businesses to buy by asking the owners
Knowing how to find off-market businesses for sale mostly comes down to asking. An off-market business is one whose owner never hired a broker or posted it on a marketplace. You write a buy box, build a list of owners from public registers, send a short and low-pressure first message, and keep following up for months. Many owners will stay silent and many who answer won't be ready yet, so treat it as a volume and patience game.
This is for founders and operators who want to buy an established company and find the broker listings picked over. Every step is ordinary outbound work, from the list to the message, the follow-up rhythm and the first call. Chrysales builds that kind of outreach for client acquisition and doesn't buy companies itself, so the deal numbers below come from published studies and buyer stories, each one linked.
What does "off-market" mean, and is it cheaper?
An off-market business is a company you can buy even though nobody is marketing it for sale. There's no broker listing and no marketplace ad, and often the owner hasn't decided to sell yet. You reach it by contacting the owner directly, which starts a conversation with the person who decides, before any auction.
The phrase also gets used for unlisted property, which is why search results mix in real estate. Here it means operating companies with staff and customers, run by an owner who might want to step back.
| Listed (broker or marketplace) | Off-market (you contact the owner) | |
|---|---|---|
| Who starts the contact | The owner, through a broker | You |
| Owner's readiness | Has decided to sell | Often undecided, sometimes years away |
| Information at the start | A teaser and a pack of numbers | Very little, until there's trust |
| Other buyers | Everyone who sees the listing | Others who wrote to the same owner |
| Your work | Screening listings and bidding | Building lists and following up for months |
Is it cheaper? Some buyers say anecdotally that they paid low prices on deals they found themselves, while others describe owners using a buyer's interest to test what the market will pay. We found no public dataset that settles the question either way, so plan without counting on a discount.
Off-market search is also slow, even for people who do it full time. Stanford GSB has tracked over 850 search funds in the US and Canada since 1996; a search fund is a person who raises investor money to find, buy and run one company. According to Stanford's 2026 write-up, 58% of those funds went on to buy a company, and "Acquiring a company typically takes around 20 months." Plan your search in quarters.
Why would an owner sell a business that isn't for sale?
Retirement is the leading reason in the one broker survey below, and many owners are close to retirement age. Your letter lands best with an owner who already has that question in the back of their mind. That's why the owner's situation belongs in your buy box, next to industry and size, and why your message should leave room for "maybe later".
The age numbers point the same way on both sides of the Atlantic. In Germany, KfW Research counted 545,000 Mittelstand companies that want to settle their succession by the end of 2029, and 57% of Mittelstand owners were 55 or older in 2025. KfW also wrote that "many business owners find the search for a suitable successor very difficult" (our translation from German).
The Census Bureau reported that over half of US employer-business owners were 55 or older. That figure comes from data collected for 2018, so treat it as dated.
Among companies that did go to market through brokers, retirement led the reasons. The IBBA and M&A Source Market Pulse survey for Q2 2026 found it was the leading reason in every deal-size segment, peaking at 72% in the $1-2M segment. That survey covers brokered deals, so read it as a hint about what makes owners sell, not as proof for unlisted companies.
Warren Buffett described the owner's side in his 1990 letter to Berkshire Hathaway shareholders. Owner-managers, he wrote, "sell their business only once", often with pressure coming from several directions. If you write like you understand that, you get read differently from a bidder.
How do you write a buy box before you contact anyone?
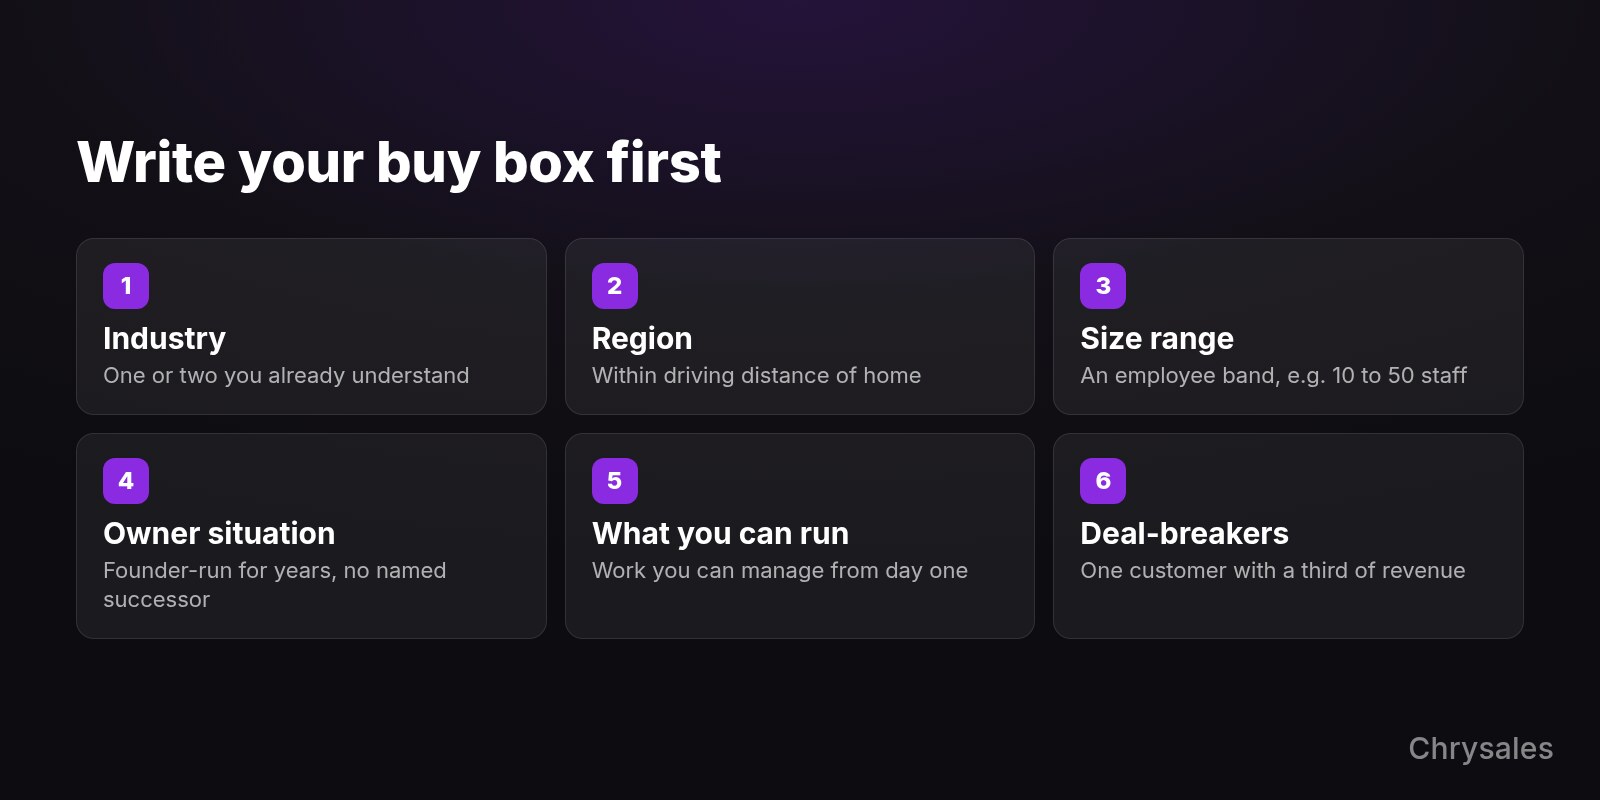
A buy box is a one-page description of the companies you will buy: industry, region, size, the owner's situation, what you can run yourself, and your deal-breakers. Write it before the first letter. It decides who goes on your list and gives your first message something specific to say. It also lets you drop a company that doesn't fit in minutes instead of weeks.
Berkshire Hathaway printed its own buy box in that same 1990 letter. Among other points it asked for "Management in place (we can't supply it)" and "Simple businesses". Berkshire buys at a scale far above yours, but the habit carries over well. Say in plain words what you want and what you can't bring to the deal.
| Criterion | Example (fill in your own) | Why it matters |
|---|---|---|
| Industry | One or two you already understand | You can judge the business and talk the owner's language |
| Region | Within driving distance of home | You will likely run it in person, at least at first |
| Size range | An employee band, e.g. 10 to 50 staff | Registers rarely show revenue, so headcount is easier to filter |
| Owner situation | Founder-run for years, no named successor | Points your list at owners with a reason to talk |
| What you can run | Work you can manage from day one | Tells you whether you need a manager who stays |
| Deal-breakers | One customer with a third of revenue | Saves months on companies you'd walk away from |
Keep it to one page and test it on a colleague. If two people read your buy box and pick different companies from the same list, it's still too loose.
Where do you find the owners of off-market businesses?
Start with public company registers filtered by your buy box, then use association directories, company websites and LinkedIn to find the owner's name and a way to reach them. In the UK that means Companies House, in Germany the Handelsregister and nexxt-change, and in the US each state's business registry. Anyone can download the same lists, so your edge comes from fit and follow-up.
- Size the market first. For a US market, the Census Bureau's County Business Patterns counts establishments by industry, county and employee size, so you can see whether your buy box holds, say, 30 companies or 3,000. The page currently notes that its information is no longer current while methods are reviewed, so use it for a rough count only.
- Pull the companies from a register. Companies House advanced search in the UK filters by nature of business (SIC code), company status, incorporation date and registered office address. Companies House also publishes a free monthly snapshot of live companies for bulk work.
- Use the German register and succession exchange. Handelsregister data has been free to view without registration since August 2022, according to the IHK Lahn-Dill. On nexxt-change, Germany's official succession exchange, buyers can post a wanted ad (Kaufgesuch) that owners can answer.
- Work the US state registries. Each state keeps its own business records, and buyers pull lists from them by industry code.
- Add association and trade-show lists. Member directories and exhibitor lists can add companies and names that a register search misses.
- Find the owner's name for each company. Check the company website and LinkedIn to confirm who owns it and still runs it day to day.
- Ask the people around owners. Accountants, lawyers and bank advisors work with owners on succession, and owners talk to each other too. A Searchfunder member put it this way: "Owner's know Owner's, so even if they are not looking to sell at the exact moment they may know someone who is."
- Keep everything in one sheet or CRM, with a row per company and columns for owner, source, fit notes and every touch.
Jed Morris, who writes the Still Searching newsletter, makes the point that registry lists sorted by industry code are open to everyone, so the list alone gives you no advantage. The edge has to come from what you do with it.
Patrick Dichter's search shows what a narrow list can do. According to a Searchfunder summary of his Acquiring Minds interview, brokers told him to come back once he had a CPA partner. So he had a list of accounting and bookkeeping firms in New England built and ran a three-message email sequence.
His funnel was 500 emails, 20 owner calls, 3 LOIs (letters of intent, the non-binding offers) and 1 closed deal. Those are one buyer's numbers, from around 2022, in one niche.
The same rules apply as when you sell and are building a narrow B2B lead list: fewer names that truly fit, checked by hand, with a note on why each one is there.
What should the first letter or email to an owner say?
Keep the first message short and about the owner. Say who you are and why you picked their company, then ask one easy question. Don't ask for a price or financials in the first touch, because an owner who hasn't decided anything won't send numbers to a stranger. Make a reply easy, including a "no".
Owners often hear from buyers. One searcher on Searchfunder wrote that sellers had said, "we get contacted by buyers every month and ignore them," so give a specific reason for writing to this company.
Michael Girdley is a holding-company operator and investor who writes Girdley's Letter. He argues that "short, custom messages always work better than long copy-pastes." The body of his example to an owner is two sentences, "Dear Jim, would you like to talk about selling your business? If so, let me know."
In a letter to an owner, which he reprinted in his 1990 shareholder letter, Buffett wrote, "I will not pester you; if you have any possible interest in selling, I would appreciate your call." That owner had already hinted he might sell, yet the tone suits a cold letter just as well.
The templates below use placeholders in square brackets. Replace every one, and cut any line you can't make specific.
A first letter, signed by hand if you can:
Dear [Owner name],

My name is [your name]. I'm looking to buy one company in [region]
and run it myself for the long term. I've spent [number] years in
[your field], and [Company name] stood out to me because [one
specific reason: how long you've been around, a project, what your
customers say about you].

I don't know whether selling is on your mind at all, now or in a
few years. If it ever is, I'd value a short, confidential
conversation. You wouldn't need to share any numbers for that.

If it isn't, a one-line reply is fine and I'll leave it there.

You can reach me at [phone] or [email].

Kind regards,
[Your name]
A short email about a week after the letter:
Subject: [Company name]

Hi [owner first name],

I sent you a letter last week. In short, I'm looking to buy and run
one company in [region], and [Company name] is the one I'd most
like to talk to because [specific reason].

Would you be open to a 20-minute call this month? No financials
needed.

If the answer is no, just reply "no" and I won't write again.

[Your name]
[Phone]
[Your postal address]
A LinkedIn connection note (under 200 characters):
Hi [first name], I'm looking to buy and run one company in [region]
for the long term, and [Company] is high on my list. Open to a
short, confidential chat? No pressure.
A phone opener, two or three weeks after the letter (check the rules for business calls in your country first):
Hi [owner name], this is [your name]. I wrote to you a couple of
weeks ago about [Company name]. Did my letter reach you?

[Pause and let them answer.]

I'm looking to buy one company in [region] and run it myself. I
have no idea whether selling is on your mind. Would it be worth
20 minutes, by phone or over coffee, to see if there's any fit,
now or later?
On LinkedIn, free accounts can add a personal note to up to three connection requests a month, each up to 200 characters, while Premium members can personalize all of them (LinkedIn Help, as of November 2026). Save the free notes for the owners at the top of your list. For the rest, send the request without a note after your letter has arrived.
For the structure behind a short first email, see how to write cold emails that get replies, and for LinkedIn, these tips for a LinkedIn connection request message. In Germany, put the letter first and check the email rules before you send.
How many times should you follow up, and over how long?
Plan on six or more touches over about six months, mixing letter, email, phone and LinkedIn, then a short check-in every quarter until the owner replies or asks you to stop. Expect the first message to go unanswered. Girdley calls this the "6th Contact Rule", which "says that you won't even get an answer until the 6th time you cross someone's desk."

Silence is the default. One Searchfunder member estimated that "98% of owners, contacted by searchers, don't respond." Read that as one person's estimate.
| Touch | When | Channel | What it says |
|---|---|---|---|
| 1 | Week 1 | Letter | Who you are, why this company, one easy question |
| 2 | Week 2 | A short note that refers to the letter | |
| 3 | Week 3-4 | Phone | Did the letter arrive? Offer a short call |
| 4 | Week 6 | Connection request, with a note for top names | |
| 5 | Month 3 | Letter | Something new and specific about their company |
| 6 | Month 6 | Email or call | Check in and ask if anything has changed |
| After that | Every quarter | Mixed | A short note until they reply or say stop |
Treat the table as a starting plan built from the buyers quoted here; nobody has tested it as a formula. If an owner says no, stop. If they say "not now", ask when you may check back and put that date in your calendar.
Mike McLean's newsletter shows what that looks like in practice. "I started with a cold email in August, and didn't get a response," he wrote. "After following up, getting rejected, and sending a hand-written letter, I finally got a call in October." He didn't publish whether a deal followed. In another story, told by Acquire and Build, the owner of an 85-year-old sheet-metal company said no, was approached again about six months later, and sold.
How many owners do you need? Here's an illustration, not a forecast. A UK searcher on Searchfunder built a list of 1,294 targets from paid lists and Companies House, sent signed letters first, then email, then LinkedIn notes, and reported email reply rates of "anything from 2-4%". At those rates, 500 owners would give you roughly 10 to 20 replies, and only some of those would want a call.
Dichter's 500 emails, for comparison, led to 20 owner calls and one closed deal.
How you send matters too. A searcher in Montreal compared channels on Searchfunder. Direct emails to 200 owners got about 10% replies, while 350 sent through a sales-email platform brought "very poor ROI (about 1%)", and he found that the platform's email system "tends to hurt your deliverability in the long term". That is one buyer in one market.
Two follow-ups you can adapt. The second letter, around month 3:
Dear [Owner name],

I wrote to you in [month] about [Company name]. I'm still looking
for one company in [region] to buy and run, and yours is still the
one I'd most like to talk to.

Since then I noticed [one new, specific thing: an anniversary, a
new location, a new hire].

If the timing is wrong, I understand. If it changes, even in a year
or two, I'd like to be the first person you call.

[Your name, phone, email]
The check-in email, around month 6:
Subject: [Company name], checking in

Hi [first name],

It's been about six months since my first letter. I'm still
looking, and [Company name] is still near the top of my list.

Has anything changed on your side? A one-word reply is plenty. If
you'd rather not hear from me again, just say so.

[Your name]
[Your postal address]
For more on spacing and wording, see these cold email follow-up timing and templates.
Which channel should lead? Sabir made the next video for founders reaching clients. It's about client outreach, but the channel question is the same when you write to owners. In it, he explains when cold email wins, when cold calling does, what each costs, and how to combine both into one outreach system that fits your stage.
What do you ask on the first call with an owner?
Use the first call to listen. Ask why they replied, what they want for themselves, their staff and their customers after a sale, and what the business depends on, then agree on a dated next step. Don't name a price and don't ask for full financials yet. You're after a second conversation and enough trust that the owner will later share the numbers.
The structure is the same as when you run a discovery call: qualify first, pitch last. These questions work in roughly this order:
- What made you reply to my letter?
- How did the business start, and what does a normal week look like for you now?
- If you stepped back, what would you want to happen to your team and your customers?
- What does the business rely on today that only you can do?
- What timing would make sense for you, if any: this year, in two years, later?
- Who else would be part of a decision, such as family, partners or an advisor?
- What would you need to see from a buyer before you'd trust them?
Question 4 matters for price later. Buyers tend to pay less for a company whose revenue depends on the owner. This guide to how a business valuation calculator works covers how owner dependence affects the sale value.
Sooner or later the owner asks, "What's your offer?" Answer without a number on the first call:
That's a fair question. I don't want to put a number on it before
I understand the business, because I'd only be guessing, and a
guess would either undersell you or mislead you. If you're open to
it, I'd like to see a summary of the last few years under an NDA.
Then I'll come back by [date] with a range and how I got to it.
End every call with a date in both calendars: a second meeting, a visit, or a check-in in three months if they aren't ready. Once real numbers are on the table, get help. The SBA's guide to buying a business tells buyers to "Consider hiring an attorney and an accountant."
Which outreach rules apply before you send?
Check how the law in your country treats a letter of interest, and ask a lawyer before you send at volume. In the US, the CAN-SPAM rules cover business email. In Germany, email advertising needs prior consent, which makes the letter the cautious first touch. UK rules differ by type of business, and collecting owners' names and contact details is personal-data processing under GDPR and UK GDPR. None of this is legal advice.
- United States. The FTC's CAN-SPAM compliance guide says "The law makes no exception for business-to-business email." Commercial emails need your valid physical postal address, and opt-out requests must be honored within 10 business days. The guide doesn't settle whether an acquisition inquiry counts as commercial, so follow the rules anyway.
- Germany. The unfair competition law (UWG §7) requires prior express consent for email advertising and at least presumed consent for calls to businesses. Whether a purchase inquiry counts as advertising, and whether your calls meet the consent rule, are questions for your lawyer, so start with a letter.
- United Kingdom. UK rules treat sole traders and some partnerships differently from companies; check the ICO's business-to-business marketing guidance, which the ICO marks as under review in 2026.
Common mistakes when approaching owners
- Asking for a price or financials in the first message. Owners who haven't decided to sell won't send numbers to a stranger. Ask for a conversation and let the numbers come after trust and an NDA.
- Sending one message and giving up. Plan all six touches before you send the first.
- Blasting generic email through a sales platform. The Montreal searcher's platform send brought what he called "very poor ROI (about 1%)", against about 10% replies for his direct emails, and he found it hurt deliverability. Write at least the first message to your top names yourself.
- Stopping your search during a deal. All four LOIs the same Montreal searcher submitted fell through. He wrote, "You need to have alternatives if the owner decides to renegotiate the deal late in the process." Keep a weekly outreach slot even when one deal looks close.
- Trusting the title "broker". Jed Morris notes that in the US "There's no legal certification or requirement to become a broker so anyone can call themselves a business broker." Ask any broker for references and recently closed deals.
- Treating "not now" as "no". The sheet-metal owner in the Acquire and Build story said no and sold about six months later. Ask when you may check back, then do it on that date.
FAQ
Are off-market businesses cheaper than listed ones?
Not according to any public data we could find. Outreach gets you an early, direct conversation with the owner, and the price still depends on the business.
Should I still talk to brokers if I'm contacting owners directly?
Yes. Brokers bring owners who have already decided to sell, and running both channels gives you more companies to compare. In the Montreal search on Searchfunder, brokers produced just over half of the companies found. Check a broker's references and track record before you rely on them.
How many owners do I need to contact to buy one business?
There's no reliable rate in the sources we checked. One UK searcher reported email reply rates of 2-4%, and Patrick Dichter's 500 emails led to 20 owner calls and one closed deal. Start with a few hundred owners who fit your buy box, and keep adding names every week.
How long does it take to find a business to buy this way?
Expect months. Jed Morris writes that first-time buyers often spend "3 - 6 months" before they talk to a real owner. Stanford found that funded search funds typically take around 20 months to buy a company.
Sources
- Stanford GSB - Search funds keep offering a proven path to ownership (2026)
- KfW - Nachfolge-Monitoring Mittelstand, press release of 9 January 2026 (German)
- US Census Bureau - Business owners' ages
- IBBA and M&A Source - Market Pulse Q2 2026 press release (PR Newswire, via Webull)
- Berkshire Hathaway - 1990 letter to shareholders
- US Census Bureau - County Business Patterns
- Companies House - Advanced company search
- GOV.UK - Companies House data products
- IHK Lahn-Dill - Handelsregister digitalization (German)
- nexxt-change - German succession exchange
- LinkedIn Help - Personalized invitations
- FTC - CAN-SPAM Act compliance guide for business
- Gesetze im Internet - UWG §7 (German)
- ICO - Business-to-business marketing
- SBA - Buy an existing business or franchise
- Michael Girdley - Cold outreach that works
- Searchfunder - Shut out by industry brokers, an entrepreneur finds a way
- Searchfunder - Proprietary sourcing methods that delivered 2 acquisitions
- Searchfunder - Takeaways after searching for 9 months in Montreal
- Searchfunder - Breaking through the barrier: SMB owners who won't talk to buyers
- Searchfunder - Best methods for contacting owners who are not actively selling
- Mike McLean - Updates and my strategy, visualized
- Acquire and Build - She said no, then sold the business anyway
- Jed Morris - So, how do I actually search for a business to buy?
Want your outreach to keep running every week, even while you're deep in one deal? Chrysales builds list, message and follow-up systems for client acquisition, and on a free strategy call you can review your own outreach rhythm with them. Its experience is in client-acquisition outreach, not in buying companies. Talk through your outreach rhythm on a free call

Knowing how to find off-market businesses for sale mostly comes down to asking. An off-market business is one whose owner never hired a broker or posted it on a marketplace. You write a buy box, build a list of owners from public registers, send a short and low-pressure first message, and keep following up for months. Many owners will stay silent and many who answer won't be ready yet, so treat it as a volume and patience game.
This is for founders and operators who want to buy an established company and find the broker listings picked over. Every step is ordinary outbound work, from the list to the message, the follow-up rhythm and the first call. Chrysales builds that kind of outreach for client acquisition and doesn't buy companies itself, so the deal numbers below come from published studies and buyer stories, each one linked.
What does "off-market" mean, and is it cheaper?
An off-market business is a company you can buy even though nobody is marketing it for sale. There's no broker listing and no marketplace ad, and often the owner hasn't decided to sell yet. You reach it by contacting the owner directly, which starts a conversation with the person who decides, before any auction.
The phrase also gets used for unlisted property, which is why search results mix in real estate. Here it means operating companies with staff and customers, run by an owner who might want to step back.
| Listed (broker or marketplace) | Off-market (you contact the owner) | |
|---|---|---|
| Who starts the contact | The owner, through a broker | You |
| Owner's readiness | Has decided to sell | Often undecided, sometimes years away |
| Information at the start | A teaser and a pack of numbers | Very little, until there's trust |
| Other buyers | Everyone who sees the listing | Others who wrote to the same owner |
| Your work | Screening listings and bidding | Building lists and following up for months |
Is it cheaper? Some buyers say anecdotally that they paid low prices on deals they found themselves, while others describe owners using a buyer's interest to test what the market will pay. We found no public dataset that settles the question either way, so plan without counting on a discount.
Off-market search is also slow, even for people who do it full time. Stanford GSB has tracked over 850 search funds in the US and Canada since 1996; a search fund is a person who raises investor money to find, buy and run one company. According to Stanford's 2026 write-up, 58% of those funds went on to buy a company, and "Acquiring a company typically takes around 20 months." Plan your search in quarters.
Why would an owner sell a business that isn't for sale?
Retirement is the leading reason in the one broker survey below, and many owners are close to retirement age. Your letter lands best with an owner who already has that question in the back of their mind. That's why the owner's situation belongs in your buy box, next to industry and size, and why your message should leave room for "maybe later".
The age numbers point the same way on both sides of the Atlantic. In Germany, KfW Research counted 545,000 Mittelstand companies that want to settle their succession by the end of 2029, and 57% of Mittelstand owners were 55 or older in 2025. KfW also wrote that "many business owners find the search for a suitable successor very difficult" (our translation from German).
The Census Bureau reported that over half of US employer-business owners were 55 or older. That figure comes from data collected for 2018, so treat it as dated.
Among companies that did go to market through brokers, retirement led the reasons. The IBBA and M&A Source Market Pulse survey for Q2 2026 found it was the leading reason in every deal-size segment, peaking at 72% in the $1-2M segment. That survey covers brokered deals, so read it as a hint about what makes owners sell, not as proof for unlisted companies.
Warren Buffett described the owner's side in his 1990 letter to Berkshire Hathaway shareholders. Owner-managers, he wrote, "sell their business only once", often with pressure coming from several directions. If you write like you understand that, you get read differently from a bidder.
How do you write a buy box before you contact anyone?
A buy box is a one-page description of the companies you will buy: industry, region, size, the owner's situation, what you can run yourself, and your deal-breakers. Write it before the first letter. It decides who goes on your list and gives your first message something specific to say. It also lets you drop a company that doesn't fit in minutes instead of weeks.
Berkshire Hathaway printed its own buy box in that same 1990 letter. Among other points it asked for "Management in place (we can't supply it)" and "Simple businesses". Berkshire buys at a scale far above yours, but the habit carries over well. Say in plain words what you want and what you can't bring to the deal.
| Criterion | Example (fill in your own) | Why it matters |
|---|---|---|
| Industry | One or two you already understand | You can judge the business and talk the owner's language |
| Region | Within driving distance of home | You will likely run it in person, at least at first |
| Size range | An employee band, e.g. 10 to 50 staff | Registers rarely show revenue, so headcount is easier to filter |
| Owner situation | Founder-run for years, no named successor | Points your list at owners with a reason to talk |
| What you can run | Work you can manage from day one | Tells you whether you need a manager who stays |
| Deal-breakers | One customer with a third of revenue | Saves months on companies you'd walk away from |
Keep it to one page and test it on a colleague. If two people read your buy box and pick different companies from the same list, it's still too loose.
Where do you find the owners of off-market businesses?
Start with public company registers filtered by your buy box, then use association directories, company websites and LinkedIn to find the owner's name and a way to reach them. In the UK that means Companies House, in Germany the Handelsregister and nexxt-change, and in the US each state's business registry. Anyone can download the same lists, so your edge comes from fit and follow-up.
- Size the market first. For a US market, the Census Bureau's County Business Patterns counts establishments by industry, county and employee size, so you can see whether your buy box holds, say, 30 companies or 3,000. The page currently notes that its information is no longer current while methods are reviewed, so use it for a rough count only.
- Pull the companies from a register. Companies House advanced search in the UK filters by nature of business (SIC code), company status, incorporation date and registered office address. Companies House also publishes a free monthly snapshot of live companies for bulk work.
- Use the German register and succession exchange. Handelsregister data has been free to view without registration since August 2022, according to the IHK Lahn-Dill. On nexxt-change, Germany's official succession exchange, buyers can post a wanted ad (Kaufgesuch) that owners can answer.
- Work the US state registries. Each state keeps its own business records, and buyers pull lists from them by industry code.
- Add association and trade-show lists. Member directories and exhibitor lists can add companies and names that a register search misses.
- Find the owner's name for each company. Check the company website and LinkedIn to confirm who owns it and still runs it day to day.
- Ask the people around owners. Accountants, lawyers and bank advisors work with owners on succession, and owners talk to each other too. A Searchfunder member put it this way: "Owner's know Owner's, so even if they are not looking to sell at the exact moment they may know someone who is."
- Keep everything in one sheet or CRM, with a row per company and columns for owner, source, fit notes and every touch.
Jed Morris, who writes the Still Searching newsletter, makes the point that registry lists sorted by industry code are open to everyone, so the list alone gives you no advantage. The edge has to come from what you do with it.
Patrick Dichter's search shows what a narrow list can do. According to a Searchfunder summary of his Acquiring Minds interview, brokers told him to come back once he had a CPA partner. So he had a list of accounting and bookkeeping firms in New England built and ran a three-message email sequence.
His funnel was 500 emails, 20 owner calls, 3 LOIs (letters of intent, the non-binding offers) and 1 closed deal. Those are one buyer's numbers, from around 2022, in one niche.
The same rules apply as when you sell and are building a narrow B2B lead list: fewer names that truly fit, checked by hand, with a note on why each one is there.
What should the first letter or email to an owner say?
Keep the first message short and about the owner. Say who you are and why you picked their company, then ask one easy question. Don't ask for a price or financials in the first touch, because an owner who hasn't decided anything won't send numbers to a stranger. Make a reply easy, including a "no".
Owners often hear from buyers. One searcher on Searchfunder wrote that sellers had said, "we get contacted by buyers every month and ignore them," so give a specific reason for writing to this company.
Michael Girdley is a holding-company operator and investor who writes Girdley's Letter. He argues that "short, custom messages always work better than long copy-pastes." The body of his example to an owner is two sentences, "Dear Jim, would you like to talk about selling your business? If so, let me know."
In a letter to an owner, which he reprinted in his 1990 shareholder letter, Buffett wrote, "I will not pester you; if you have any possible interest in selling, I would appreciate your call." That owner had already hinted he might sell, yet the tone suits a cold letter just as well.
The templates below use placeholders in square brackets. Replace every one, and cut any line you can't make specific.
A first letter, signed by hand if you can:
Dear [Owner name],

My name is [your name]. I'm looking to buy one company in [region]
and run it myself for the long term. I've spent [number] years in
[your field], and [Company name] stood out to me because [one
specific reason: how long you've been around, a project, what your
customers say about you].

I don't know whether selling is on your mind at all, now or in a
few years. If it ever is, I'd value a short, confidential
conversation. You wouldn't need to share any numbers for that.

If it isn't, a one-line reply is fine and I'll leave it there.

You can reach me at [phone] or [email].

Kind regards,
[Your name]
A short email about a week after the letter:
Subject: [Company name]

Hi [owner first name],

I sent you a letter last week. In short, I'm looking to buy and run
one company in [region], and [Company name] is the one I'd most
like to talk to because [specific reason].

Would you be open to a 20-minute call this month? No financials
needed.

If the answer is no, just reply "no" and I won't write again.

[Your name]
[Phone]
[Your postal address]
A LinkedIn connection note (under 200 characters):
Hi [first name], I'm looking to buy and run one company in [region]
for the long term, and [Company] is high on my list. Open to a
short, confidential chat? No pressure.
A phone opener, two or three weeks after the letter (check the rules for business calls in your country first):
Hi [owner name], this is [your name]. I wrote to you a couple of
weeks ago about [Company name]. Did my letter reach you?

[Pause and let them answer.]

I'm looking to buy one company in [region] and run it myself. I
have no idea whether selling is on your mind. Would it be worth
20 minutes, by phone or over coffee, to see if there's any fit,
now or later?
On LinkedIn, free accounts can add a personal note to up to three connection requests a month, each up to 200 characters, while Premium members can personalize all of them (LinkedIn Help, as of November 2026). Save the free notes for the owners at the top of your list. For the rest, send the request without a note after your letter has arrived.
For the structure behind a short first email, see how to write cold emails that get replies, and for LinkedIn, these tips for a LinkedIn connection request message. In Germany, put the letter first and check the email rules before you send.
How many times should you follow up, and over how long?
Plan on six or more touches over about six months, mixing letter, email, phone and LinkedIn, then a short check-in every quarter until the owner replies or asks you to stop. Expect the first message to go unanswered. Girdley calls this the "6th Contact Rule", which "says that you won't even get an answer until the 6th time you cross someone's desk."
Silence is the default. One Searchfunder member estimated that "98% of owners, contacted by searchers, don't respond." Read that as one person's estimate.
| Touch | When | Channel | What it says |
|---|---|---|---|
| 1 | Week 1 | Letter | Who you are, why this company, one easy question |
| 2 | Week 2 | A short note that refers to the letter | |
| 3 | Week 3-4 | Phone | Did the letter arrive? Offer a short call |
| 4 | Week 6 | Connection request, with a note for top names | |
| 5 | Month 3 | Letter | Something new and specific about their company |
| 6 | Month 6 | Email or call | Check in and ask if anything has changed |
| After that | Every quarter | Mixed | A short note until they reply or say stop |
Treat the table as a starting plan built from the buyers quoted here; nobody has tested it as a formula. If an owner says no, stop. If they say "not now", ask when you may check back and put that date in your calendar.
Mike McLean's newsletter shows what that looks like in practice. "I started with a cold email in August, and didn't get a response," he wrote. "After following up, getting rejected, and sending a hand-written letter, I finally got a call in October." He didn't publish whether a deal followed. In another story, told by Acquire and Build, the owner of an 85-year-old sheet-metal company said no, was approached again about six months later, and sold.
How many owners do you need? Here's an illustration, not a forecast. A UK searcher on Searchfunder built a list of 1,294 targets from paid lists and Companies House, sent signed letters first, then email, then LinkedIn notes, and reported email reply rates of "anything from 2-4%". At those rates, 500 owners would give you roughly 10 to 20 replies, and only some of those would want a call.
Dichter's 500 emails, for comparison, led to 20 owner calls and one closed deal.
How you send matters too. A searcher in Montreal compared channels on Searchfunder. Direct emails to 200 owners got about 10% replies, while 350 sent through a sales-email platform brought "very poor ROI (about 1%)", and he found that the platform's email system "tends to hurt your deliverability in the long term". That is one buyer in one market.
Two follow-ups you can adapt. The second letter, around month 3:
Dear [Owner name],

I wrote to you in [month] about [Company name]. I'm still looking
for one company in [region] to buy and run, and yours is still the
one I'd most like to talk to.

Since then I noticed [one new, specific thing: an anniversary, a
new location, a new hire].

If the timing is wrong, I understand. If it changes, even in a year
or two, I'd like to be the first person you call.

[Your name, phone, email]
The check-in email, around month 6:
Subject: [Company name], checking in

Hi [first name],

It's been about six months since my first letter. I'm still
looking, and [Company name] is still near the top of my list.

Has anything changed on your side? A one-word reply is plenty. If
you'd rather not hear from me again, just say so.

[Your name]
[Your postal address]
For more on spacing and wording, see these cold email follow-up timing and templates.
Which channel should lead? Sabir made the next video for founders reaching clients. It's about client outreach, but the channel question is the same when you write to owners. In it, he explains when cold email wins, when cold calling does, what each costs, and how to combine both into one outreach system that fits your stage.
What do you ask on the first call with an owner?
Use the first call to listen. Ask why they replied, what they want for themselves, their staff and their customers after a sale, and what the business depends on, then agree on a dated next step. Don't name a price and don't ask for full financials yet. You're after a second conversation and enough trust that the owner will later share the numbers.
The structure is the same as when you run a discovery call: qualify first, pitch last. These questions work in roughly this order:
- What made you reply to my letter?
- How did the business start, and what does a normal week look like for you now?
- If you stepped back, what would you want to happen to your team and your customers?
- What does the business rely on today that only you can do?
- What timing would make sense for you, if any: this year, in two years, later?
- Who else would be part of a decision, such as family, partners or an advisor?
- What would you need to see from a buyer before you'd trust them?
Question 4 matters for price later. Buyers tend to pay less for a company whose revenue depends on the owner. This guide to how a business valuation calculator works covers how owner dependence affects the sale value.
Sooner or later the owner asks, "What's your offer?" Answer without a number on the first call:
That's a fair question. I don't want to put a number on it before
I understand the business, because I'd only be guessing, and a
guess would either undersell you or mislead you. If you're open to
it, I'd like to see a summary of the last few years under an NDA.
Then I'll come back by [date] with a range and how I got to it.
End every call with a date in both calendars: a second meeting, a visit, or a check-in in three months if they aren't ready. Once real numbers are on the table, get help. The SBA's guide to buying a business tells buyers to "Consider hiring an attorney and an accountant."
Which outreach rules apply before you send?
Check how the law in your country treats a letter of interest, and ask a lawyer before you send at volume. In the US, the CAN-SPAM rules cover business email. In Germany, email advertising needs prior consent, which makes the letter the cautious first touch. UK rules differ by type of business, and collecting owners' names and contact details is personal-data processing under GDPR and UK GDPR. None of this is legal advice.
- United States. The FTC's CAN-SPAM compliance guide says "The law makes no exception for business-to-business email." Commercial emails need your valid physical postal address, and opt-out requests must be honored within 10 business days. The guide doesn't settle whether an acquisition inquiry counts as commercial, so follow the rules anyway.
- Germany. The unfair competition law (UWG §7) requires prior express consent for email advertising and at least presumed consent for calls to businesses. Whether a purchase inquiry counts as advertising, and whether your calls meet the consent rule, are questions for your lawyer, so start with a letter.
- United Kingdom. UK rules treat sole traders and some partnerships differently from companies; check the ICO's business-to-business marketing guidance, which the ICO marks as under review in 2026.
Common mistakes when approaching owners
- Asking for a price or financials in the first message. Owners who haven't decided to sell won't send numbers to a stranger. Ask for a conversation and let the numbers come after trust and an NDA.
- Sending one message and giving up. Plan all six touches before you send the first.
- Blasting generic email through a sales platform. The Montreal searcher's platform send brought what he called "very poor ROI (about 1%)", against about 10% replies for his direct emails, and he found it hurt deliverability. Write at least the first message to your top names yourself.
- Stopping your search during a deal. All four LOIs the same Montreal searcher submitted fell through. He wrote, "You need to have alternatives if the owner decides to renegotiate the deal late in the process." Keep a weekly outreach slot even when one deal looks close.
- Trusting the title "broker". Jed Morris notes that in the US "There's no legal certification or requirement to become a broker so anyone can call themselves a business broker." Ask any broker for references and recently closed deals.
- Treating "not now" as "no". The sheet-metal owner in the Acquire and Build story said no and sold about six months later. Ask when you may check back, then do it on that date.
FAQ
Are off-market businesses cheaper than listed ones?
Not according to any public data we could find. Outreach gets you an early, direct conversation with the owner, and the price still depends on the business.
Should I still talk to brokers if I'm contacting owners directly?
Yes. Brokers bring owners who have already decided to sell, and running both channels gives you more companies to compare. In the Montreal search on Searchfunder, brokers produced just over half of the companies found. Check a broker's references and track record before you rely on them.
How many owners do I need to contact to buy one business?
There's no reliable rate in the sources we checked. One UK searcher reported email reply rates of 2-4%, and Patrick Dichter's 500 emails led to 20 owner calls and one closed deal. Start with a few hundred owners who fit your buy box, and keep adding names every week.
How long does it take to find a business to buy this way?
Expect months. Jed Morris writes that first-time buyers often spend "3 - 6 months" before they talk to a real owner. Stanford found that funded search funds typically take around 20 months to buy a company.
Sources
- Stanford GSB - Search funds keep offering a proven path to ownership (2026)
- KfW - Nachfolge-Monitoring Mittelstand, press release of 9 January 2026 (German)
- US Census Bureau - Business owners' ages
- IBBA and M&A Source - Market Pulse Q2 2026 press release (PR Newswire, via Webull)
- Berkshire Hathaway - 1990 letter to shareholders
- US Census Bureau - County Business Patterns
- Companies House - Advanced company search
- GOV.UK - Companies House data products
- IHK Lahn-Dill - Handelsregister digitalization (German)
- nexxt-change - German succession exchange
- LinkedIn Help - Personalized invitations
- FTC - CAN-SPAM Act compliance guide for business
- Gesetze im Internet - UWG §7 (German)
- ICO - Business-to-business marketing
- SBA - Buy an existing business or franchise
- Michael Girdley - Cold outreach that works
- Searchfunder - Shut out by industry brokers, an entrepreneur finds a way
- Searchfunder - Proprietary sourcing methods that delivered 2 acquisitions
- Searchfunder - Takeaways after searching for 9 months in Montreal
- Searchfunder - Breaking through the barrier: SMB owners who won't talk to buyers
- Searchfunder - Best methods for contacting owners who are not actively selling
- Mike McLean - Updates and my strategy, visualized
- Acquire and Build - She said no, then sold the business anyway
- Jed Morris - So, how do I actually search for a business to buy?
Want your outreach to keep running every week, even while you're deep in one deal? Chrysales builds list, message and follow-up systems for client acquisition, and on a free strategy call you can review your own outreach rhythm with them. Its experience is in client-acquisition outreach, not in buying companies. Talk through your outreach rhythm on a free call
Scaling Is Not Hard If You Have The Right Systems
If you’re serious about leveling up your scaling game, you need the right system, the right training, and the right team behind you. We're here to give you the exact tools and strategies top entrepreneurs use to dominate.
Discover the latest tips
View All
Chrysales was formed from the words "chrysalis" the stage where a caterpillar transforms into a butterfly and "sales".
It stands for one thing: sales transformation.Because scaling doesn’t happen by doing more of the same. Scaling only happens when you go through real transformation in your systems, your offer, team and the way you sell.


