
Seller financing when buying a business: how the deal works
Seller financing means the seller lets you pay part of the price over time, through a promissory note you sign at closing. When you buy a business with seller financing, you usually pay the bigger part at closing, from your own cash and often a bank or SBA loan. You owe the seller the rest. In the US, one condition shapes the deal. If an SBA 7(a) loan is involved, the seller note counts toward your down payment only on full standby, with no payments for the whole loan term.
The rules below are US rules, as of November 2026. If you're buying in the UK or the DACH region, vendor finance follows different rules there, so check them locally. Nothing here is legal, tax or lending advice: have a lawyer, a CPA and your lender look at your own deal before you sign.
What is seller financing when you buy a business?
Seller financing is a loan from the seller to you for part of the purchase price. Instead of receiving everything at closing, the seller accepts a promissory note, usually called a seller note, and you pay it back with interest out of the business's cash flow. It sits next to your own cash and, in many deals, a bank or SBA loan that gets paid before the seller.
You'll also see it called owner financing. Either way, the seller becomes one of your creditors. The terms live in the note itself, plus a security agreement if the seller takes collateral, and they're negotiated deal by deal.
A seller note is usually a slice of the price, not the whole thing. In the IBBA and M&A Source Market Pulse survey for Q2 2026, which covered 255 advisors and 181 closed deals, seller financing averaged between 6% and 11% of deal value depending on deal size. The highest share, 11%, was in deals under $500,000.
Don't confuse a seller note with an earnout. A seller note is a fixed debt you owe whatever happens. An earnout is an extra payment that depends on how the business performs after closing, and SBA deals don't allow it.
Which terms do you negotiate in a seller note?
You negotiate the amount, the interest rate, the term and payment schedule, and whether there's a balloon. Then come the security the seller gets, any personal guaranty, what counts as default and where the note ranks behind a bank. Published ranges disagree with each other, so treat every range as one source's view and test it against your lender's rules and your own cash flow.
| Item | What it means | What sources say | What to watch |
|---|---|---|---|
| Share of price | How much of the price the note covers | IBBA Q2 2026: 6% to 11% of deal value on average, by deal size | In an SBA deal, a standby note can cover at most half of your 10% injection |
| Down payment | Cash you pay at closing | Surge Business Law: 10% to 50% of the price; SBA: at least 10% injection for a first acquisition | The SBA minimum for an initial acquisition can't be reduced |
| Interest rate | Yearly rate on the note | Surge: 5% to 8%; an SBA lender on searchfunder: 5% to 6%, "7-8% max" | Below the IRS applicable federal rate, part of the principal can be taxed as interest |
| Term | How long you pay | Surge: most notes run 3 to 7 years | A long payment schedule with a short term leaves a balloon |
| Balloon | A lump sum due at the end | No common range found | The SBA loan itself may not have a balloon |
| Security | Collateral the seller can claim, usually filed as a UCC-1 | A UCC-1 lapses after five years unless continued | On SBA standby, the seller must subordinate any lien to the lender's |
| Personal guaranty | You sign for the note with your own assets | Varies by deal; no published range found | Ask when it ends and what it covers |
| Default terms | What counts as default and how long you have to fix it | None verified | Acceleration lets the seller demand the full balance |
| Ranking | Whether the note is paid before or after the bank | The SBA requires subordination for standby notes | The searchfunder lender warns that a seller who earns the same or more than the bank but is paid last causes issues |
| Set-off | Your right to deduct claims against the seller from the note | Seen in the ONAR 8-K below | Protects you if the seller's statements turn out to be wrong |
The rate has a tax floor. If the note's interest is too low, the IRS uses the applicable federal rate (AFR) to treat part of the principal as interest. For October 2026, the annual AFRs were 4.25% short-term, 4.61% mid-term and 5.22% long-term, and the table for the month of your sale is the one that applies.
For a real clause set, read ONAR Holding Corporation's 8-K filing on buying Advertise Purple. The buyer paid $12.825 million in cash, issued a $7.0 million unsecured, subordinated seller note and added an earnout of up to $8.0 million. The note carries 8.0% simple interest paid quarterly, and all principal is due at 36 months, so it ends in a balloon. The parent company backs the note with a guaranty, and the buyer can set off indemnification claims against the principal.
That's a large deal outside the SBA program. Use it as a list of clauses to discuss, not as a benchmark for your numbers.
How does a seller note work with an SBA 7(a) loan since October 2026?
Since October 1, 2026, the SBA's SOP 50 10 8.1 counts a seller note toward your equity injection only if it's subordinated to the lender and on full standby. Full standby means no principal or interest payments for the whole 7(a) loan term. The seller note shares a cap with a few other soft sources of equity, like money from a minority investor. Together they can cover at most half of your 10%, so at least 5% of the project cost has to come from elsewhere, usually your own cash.
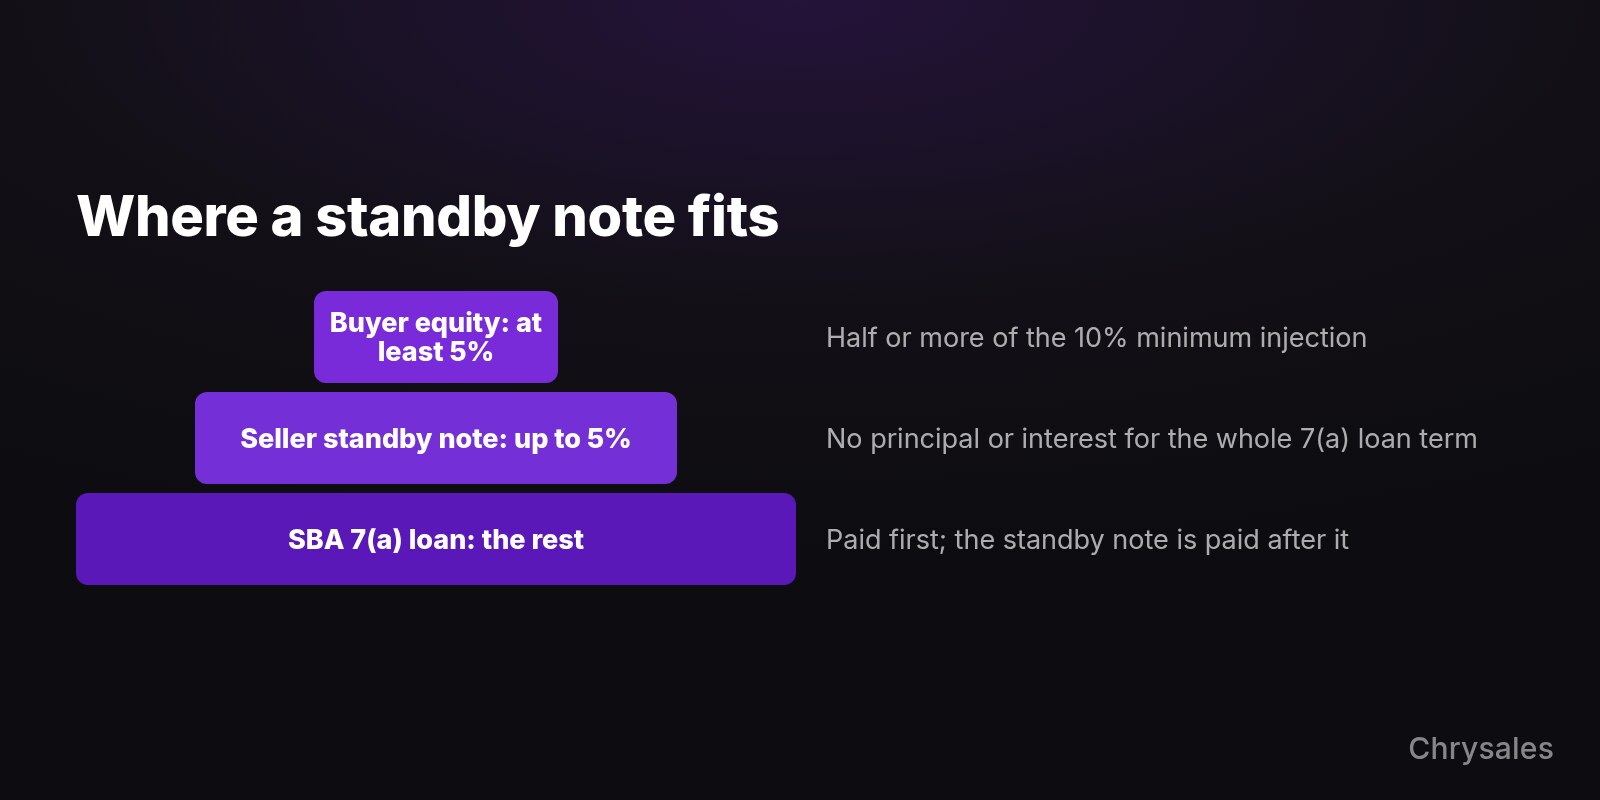
SOP 50 10 8.1 applies to 7(a) applications that receive an SBA loan number on or after October 1, 2026. The full text sits in Appendix 15 of the SOP, under the limited sources of equity injection, on the SBA's SOP 50 10 page. The SBA rules in this section were checked against that SOP text; where lender and law firm blogs word them differently, they're named.
The minimum equity injection for an initial acquisition is 10% of total project cost, and it can't be reduced. Seller debt on standby, other standby debt and minority investor equity share one cap: together they can provide no more than half of that injection.
Half of 10% is 5% of project cost. That's why some write-ups say "50%" and others say "5%". Live Oak Bank, for example, describes a seller note covering "up to 5%" of the requirement.
Full standby doesn't mean the seller gives up interest. The standby debt may accrue interest, which can be added to the note and paid after the 7(a) loan is repaid. Until then, the seller has to subordinate any lien rights to the lender and can't act against you without the lender's consent, usually through SBA Form 155 or the lender's own standby agreement.
Not every seller note has to be on standby. A note that isn't counted as equity can have normal payments, but the lender includes it in your debt service coverage. Other SOP 50 10 8.1 rules that touch the seller note:
- Total debt, including a paying seller note, is capped at the business valuation.
- If a paying seller note is interest-only, the lender has to size it on an amortization of no more than 10 years.
- Debt service coverage must be at least 1.25 for an initial acquisition, up from 1.15 under the previous SOP 50 10 8. It's measured on the last fiscal year or the average of the last two, not on projections (owner-occupied special purpose property is the exception).
- A quality of earnings report is required when the purchase price is $3 million or more, measured before seller debt.
- If you pay more than the business valuation, the difference has to be covered by equity.
- The 7(a) loan can't have a balloon, and the business part can't amortize over more than 10 years.
- The seller can stay on as a consultant for up to 24 months in total.
- A seller who keeps less than 20% of the business must give a full guaranty for the whole loan for at least two years after final disbursement.
Seller earnouts are not allowed in these deals, though buyer rebates based on business performance are. Blake Cantrell, Partner Attorney at Cantrell Law Firm, puts it plainly: "If your deal needs an earnout to bridge a valuation gap, it generally cannot be financed with an SBA loan".
Some older articles and forum threads still say the seller note only has to sit for 24 months. That was the rule under SOP 50 10 7.1 from November 2023, which allowed full or partial standby for the first 24 months. Full standby for the life of the loan started with SOP 50 10 8 in June 2025 and stays in 8.1.
Two buyer stories show the change. Doug Breaker, owner of Shoeboxed, describes splitting his seller financing into a paying note and a standby note with no payments for 24 months. That matches the older rule, and his page says its figures are approximations.
Jimmy Feeman, in a Baton case study on buying Silver Creek Exteriors, asked for 5% of the deal as a separate seller note deferred for 10 years until the SBA loan is paid off. That second shape is what the current rule asks of a standby note.
What does a seller-financed deal look like in numbers?
Take a fictional deal with a total project cost of $1,000,000, a 10-year SBA loan at an assumed 10% rate and a seller note at an assumed 7%. The structure changes how much cash you bring, what you pay each month and how much EBITDA a lender wants to see at 1.25x coverage. The three versions below were calculated with the standard amortization formula and monthly payments.
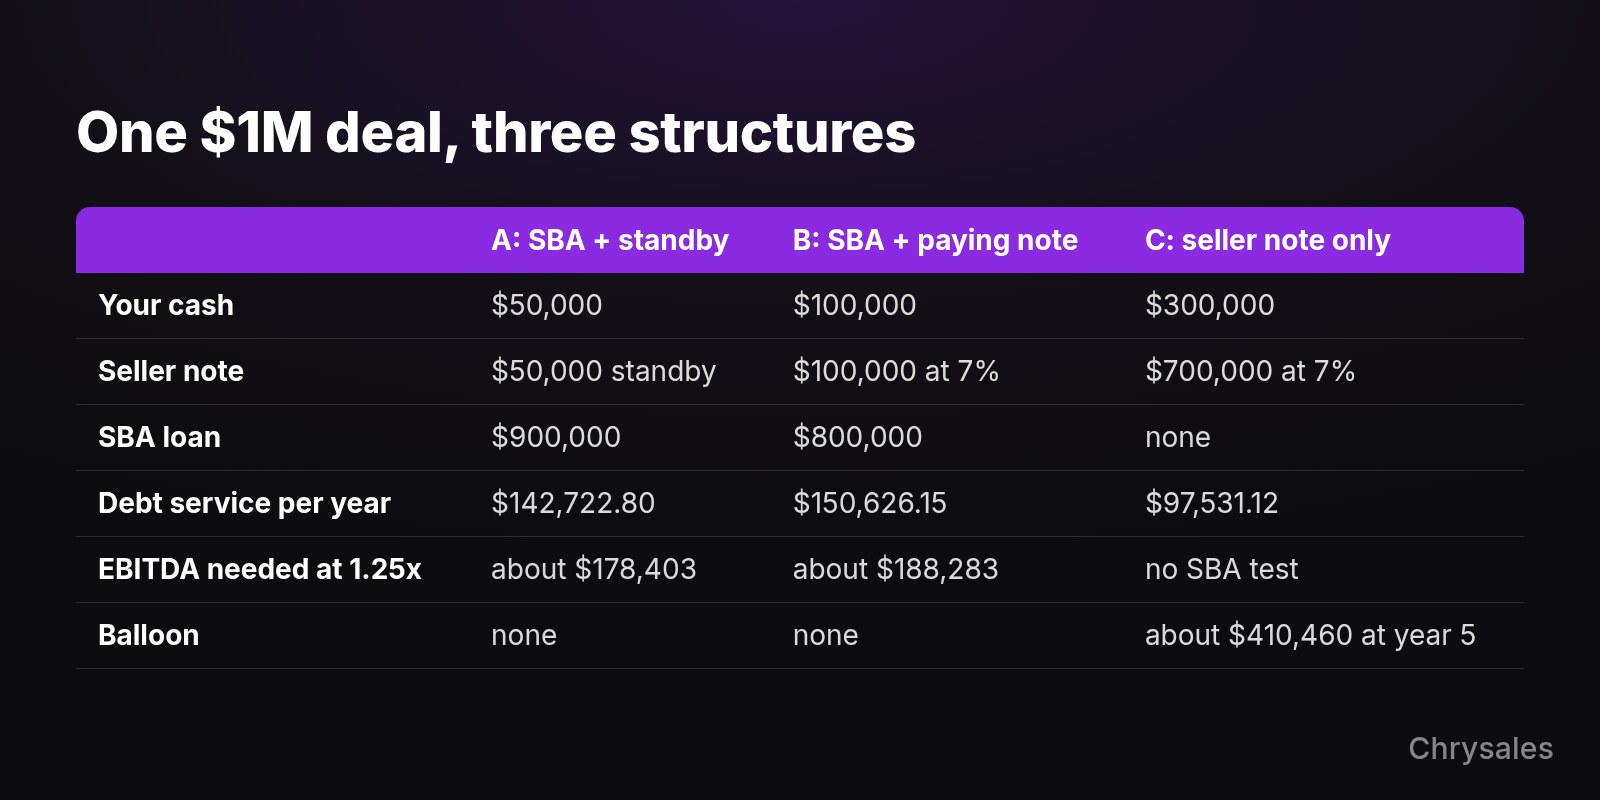
The 10% SBA rate and the 7% seller rates are assumptions for illustration, not quotes. Put in your lender's rate and the rate you agree with the seller before you rely on any of this.
| A: SBA loan + standby note | B: SBA loan + paying note | C: seller note only | |
|---|---|---|---|
| Your cash | $50,000 | $100,000 | $300,000 |
| Seller note | $50,000 on full standby | $100,000 at 7% over 5 years | $700,000 at 7%, 10-year amortization |
| SBA loan | $900,000 | $800,000 | none |
| Monthly payments | $11,893.57 | $10,572.06 + $1,980.12 | $8,127.59 |
| Debt service per year | $142,722.80 | $150,626.15 | $97,531.12 |
| EBITDA needed at 1.25x | about $178,403 | about $188,283 | no SBA test |
| Balloon | none | none | about $410,460 at year 5 |
In structure A you bring the least cash, and you make no payments on the standby note for 10 years. The seller waits that whole time. If the note accrues interest at an assumed 6%, compounded yearly, the $50,000 grows to about $89,542 by the time the SBA loan is repaid.
Structure B needs twice your cash, and because the seller note pays from day one, it counts in debt service coverage. The lender wants about $188,283 of EBITDA instead of about $178,403. EBITDA here means earnings before interest, taxes, depreciation and amortization, which is the figure SBA lenders divide by debt service.
Structure C skips the bank and has the lowest monthly payment. The catch is the year-5 balloon of about $410,460, which you have to pay or refinance, and a seller who carries 70% of the project cost on their own balance sheet.
How do you ask a seller to finance part of the price?
Ask in a fixed order: price and the valuation behind it first, then the size of the note and how much sits on standby. Rate and term come next, then security, guaranty and default terms, and the seller's role after closing comes last. Put the note's main terms, including any standby, in the letter of intent so they don't come up for the first time when the lender reviews the file.

- Settle the price and how you got there. Know what the business is worth before you size any debt, because in an SBA deal anything you pay above the valuation has to be covered by equity.
- Size the note and split it. Decide which part of the seller note goes on full standby to count toward your injection and which part, if any, pays from day one. Write both into the letter of intent (LOI), the short non-binding document that sets the main terms before diligence.
- Agree on rate and term. Start from the applicable federal rate as the tax floor, and check with your lender before you offer the seller more than the bank's rate.
- Agree on security and any guaranty. Say what the seller gets as collateral, how the UCC-1 is filed and continued, and whether a personal guaranty ends after a set period.
- Write the default terms. Define what counts as default, how long you have to fix it, when the seller can demand the full balance, and your right to set off claims.
- Set the seller's transition role. SBA deals let the seller consult for up to 24 months in total, so agree on what they do and for how long.
It helps to know why a seller says yes or no, and the tax side explains a lot of pushback. A sale with at least one payment after the tax year of the sale is an installment sale for the IRS, reported on Form 6252. The interest the seller earns is generally ordinary income.
Inventory can't be reported on the installment method, and depreciation recapture is taxed in the year of the sale. So a seller can owe tax before the note has paid them anything. Those are questions for the seller's CPA.
Standby is the harder ask. A seller on full standby gets no payments for the whole 7(a) loan term. With a 10-year SBA loan, as in Structure A of the $1M example, that means 10 years. If you found the business by approaching the owner before a listing exists, there may be no broker in the middle, so you'll explain this to the owner yourself.
What can go wrong after closing?
Most problems after closing come from cash flow, paperwork or the old owner leaving. If revenue drops, you can fall behind on the note, and the seller can call a default and act on any security. A seller on full standby waits for the whole SBA loan term, and a UCC-1 that nobody continues lapses after five years. And if clients follow the old owner out, the money for the note leaves with them.
Default is where the note's wording matters most. Outside the SBA, the seller's options depend on the default and acceleration clauses you signed. With an SBA loan in the deal, a standby seller can't take action against you or the collateral without the lender's consent.
Paperwork fails quietly. A filed UCC-1 is effective for five years, and a continuation can only be filed in the last six months before it expires. On a 7- or 10-year note, someone has to put that date in a calendar. Refinancing is slow too: to refinance a seller note with an SBA loan, it must have been in place and current, not on standby, for at least 36 months.
The last risk is the owner. If clients buy because of the person who runs the company, and that person is leaving, your pipeline may leave too. A business with revenue that depends on the owner can lose clients when the owner steps back, and your note payments come out of the same cash. In diligence, ask who holds the top client relationships, how much revenue sits with the largest clients, and who closed the last ten deals.
At Chrysales, we'd treat the handover of client relationships as part of the deal itself. Use the seller's consulting period for introductions, and start setting up revenue operations that don't depend on one person in the first months, while the seller is still around.
Checklist before you sign
Three people should read the deal before you sign: a lawyer for the note and security documents, a CPA for the tax side on both ends, and your lender for the SBA rules. Go through this list with all three and settle any open points before you sign.
- The price is backed by a valuation, and any amount above it is covered by equity.
- Your injection is at least 10% of total project cost, and no more than half of it comes from standby and other limited sources.
- Any seller note counted as equity is subordinated and on full standby for the whole 7(a) loan term, with a signed SBA Form 155 or the lender's equivalent.
- Your historical EBITDA covers all debt service, including any paying seller note, at least 1.25 times.
- The note's rate is at or above the applicable federal rate for the month of the sale.
- The note states term, payment schedule, balloon if any, prepayment, default, cure period and acceleration.
- Security is described, the UCC-1 continuation date is in a calendar, and any personal guaranty has a clear end.
- There's no earnout if an SBA loan is involved, and the seller's consulting role stays within 24 months.
- You know who holds the main client relationships and how they'll be introduced to you.
FAQ
Can you buy a business with no money down using seller financing?
Don't plan on it. For an SBA 7(a) initial acquisition, the equity injection is at least 10% of project cost, and a standby seller note can cover no more than half of it. Without an SBA loan, the down payment is whatever you and the seller agree, and Surge Business Law puts the usual range at 10% to 50% of the price.
Can the seller note be the down payment for an SBA loan?
Part of it can. Under SOP 50 10 8.1, a seller note counts as equity only if it's subordinated to the lender and on full standby for the whole loan term. Together with other limited sources it can cover at most half of the required 10% injection, which is 5% of project cost.
What interest rate is normal on a seller note?
There's no official benchmark. Surge Business Law says seller financing rates typically range from 5% to 8%, while an SBA lender on searchfunder sees 5% to 6%, with 7% to 8% as a maximum. The rate shouldn't fall below the IRS applicable federal rate for the month of the sale, which was 4.61% mid-term in October 2026.
What happens if the buyer defaults on a seller note?
It depends on the note. For a note without SBA standby, the seller's options are the default and acceleration clauses in the note and any collateral that was properly filed. If the note is on SBA standby, the seller has to subordinate lien rights and can't take action without the lender's consent.
Is owner financing a good idea for the seller?
It can be, with conditions. The seller earns interest, which the IRS generally treats as ordinary income, and reports the sale as an installment sale on Form 6252. The risks are a buyer who defaults, depreciation recapture taxed in the year of sale, and, in SBA deals, a standby note that pays nothing until the 7(a) loan is repaid.
Sources
- SBA - SOP 50 10: Lender and Development Company Loan Programs (SOP 50 10 8.1, Appendix 15)
- SBA Information Notice 5000-880695 - Issuance of SOP 50 10 8.1 (copy hosted by Coleman Report)
- IRS - Topic no. 705, Installment sales
- IRS - Publication 537, Installment Sales
- IRS - Rev. Rul. 2026-19, applicable federal rates for October 2026
- Cornell Law School LII - UCC 9-515, duration of a financing statement
- IBBA and M&A Source - Market Pulse Q2 2026 highlights
- IBBA Q2 2026 Market Pulse release (via Webull)
- Surge Business Law - Seller Financing When Buying a Business: How It Works
- searchfunder - How to Structure Seller Financing the Right Way
- Live Oak Bank - SBA SOP 50 10 8: Key 2025 Updates and What's New
- Cantrell Law Firm - Selling Your Business? The SBA Just Changed the Math
- SEC - ONAR Holding Corporation Form 8-K
- Baton - How a Franchise Founder Bought a Cash-Flowing Construction Business (Jimmy Feeman, Silver Creek Exteriors)
- Shoeboxed - SBA Loan Down Payment: How I Bought a $1M+ Business for 5% Down (And A Warning)
Buying a company whose clients still call the old owner? A free strategy call with Chrysales is a place to talk through the client acquisition system that business needs, so the pipeline doesn't depend on the seller's relationships. Plan the sales handover for your acquisition on a free call

Seller financing means the seller lets you pay part of the price over time, through a promissory note you sign at closing. When you buy a business with seller financing, you usually pay the bigger part at closing, from your own cash and often a bank or SBA loan. You owe the seller the rest. In the US, one condition shapes the deal. If an SBA 7(a) loan is involved, the seller note counts toward your down payment only on full standby, with no payments for the whole loan term.
The rules below are US rules, as of November 2026. If you're buying in the UK or the DACH region, vendor finance follows different rules there, so check them locally. Nothing here is legal, tax or lending advice: have a lawyer, a CPA and your lender look at your own deal before you sign.
What is seller financing when you buy a business?
Seller financing is a loan from the seller to you for part of the purchase price. Instead of receiving everything at closing, the seller accepts a promissory note, usually called a seller note, and you pay it back with interest out of the business's cash flow. It sits next to your own cash and, in many deals, a bank or SBA loan that gets paid before the seller.
You'll also see it called owner financing. Either way, the seller becomes one of your creditors. The terms live in the note itself, plus a security agreement if the seller takes collateral, and they're negotiated deal by deal.
A seller note is usually a slice of the price, not the whole thing. In the IBBA and M&A Source Market Pulse survey for Q2 2026, which covered 255 advisors and 181 closed deals, seller financing averaged between 6% and 11% of deal value depending on deal size. The highest share, 11%, was in deals under $500,000.
Don't confuse a seller note with an earnout. A seller note is a fixed debt you owe whatever happens. An earnout is an extra payment that depends on how the business performs after closing, and SBA deals don't allow it.
Which terms do you negotiate in a seller note?
You negotiate the amount, the interest rate, the term and payment schedule, and whether there's a balloon. Then come the security the seller gets, any personal guaranty, what counts as default and where the note ranks behind a bank. Published ranges disagree with each other, so treat every range as one source's view and test it against your lender's rules and your own cash flow.
| Item | What it means | What sources say | What to watch |
|---|---|---|---|
| Share of price | How much of the price the note covers | IBBA Q2 2026: 6% to 11% of deal value on average, by deal size | In an SBA deal, a standby note can cover at most half of your 10% injection |
| Down payment | Cash you pay at closing | Surge Business Law: 10% to 50% of the price; SBA: at least 10% injection for a first acquisition | The SBA minimum for an initial acquisition can't be reduced |
| Interest rate | Yearly rate on the note | Surge: 5% to 8%; an SBA lender on searchfunder: 5% to 6%, "7-8% max" | Below the IRS applicable federal rate, part of the principal can be taxed as interest |
| Term | How long you pay | Surge: most notes run 3 to 7 years | A long payment schedule with a short term leaves a balloon |
| Balloon | A lump sum due at the end | No common range found | The SBA loan itself may not have a balloon |
| Security | Collateral the seller can claim, usually filed as a UCC-1 | A UCC-1 lapses after five years unless continued | On SBA standby, the seller must subordinate any lien to the lender's |
| Personal guaranty | You sign for the note with your own assets | Varies by deal; no published range found | Ask when it ends and what it covers |
| Default terms | What counts as default and how long you have to fix it | None verified | Acceleration lets the seller demand the full balance |
| Ranking | Whether the note is paid before or after the bank | The SBA requires subordination for standby notes | The searchfunder lender warns that a seller who earns the same or more than the bank but is paid last causes issues |
| Set-off | Your right to deduct claims against the seller from the note | Seen in the ONAR 8-K below | Protects you if the seller's statements turn out to be wrong |
The rate has a tax floor. If the note's interest is too low, the IRS uses the applicable federal rate (AFR) to treat part of the principal as interest. For October 2026, the annual AFRs were 4.25% short-term, 4.61% mid-term and 5.22% long-term, and the table for the month of your sale is the one that applies.
For a real clause set, read ONAR Holding Corporation's 8-K filing on buying Advertise Purple. The buyer paid $12.825 million in cash, issued a $7.0 million unsecured, subordinated seller note and added an earnout of up to $8.0 million. The note carries 8.0% simple interest paid quarterly, and all principal is due at 36 months, so it ends in a balloon. The parent company backs the note with a guaranty, and the buyer can set off indemnification claims against the principal.
That's a large deal outside the SBA program. Use it as a list of clauses to discuss, not as a benchmark for your numbers.
How does a seller note work with an SBA 7(a) loan since October 2026?
Since October 1, 2026, the SBA's SOP 50 10 8.1 counts a seller note toward your equity injection only if it's subordinated to the lender and on full standby. Full standby means no principal or interest payments for the whole 7(a) loan term. The seller note shares a cap with a few other soft sources of equity, like money from a minority investor. Together they can cover at most half of your 10%, so at least 5% of the project cost has to come from elsewhere, usually your own cash.
SOP 50 10 8.1 applies to 7(a) applications that receive an SBA loan number on or after October 1, 2026. The full text sits in Appendix 15 of the SOP, under the limited sources of equity injection, on the SBA's SOP 50 10 page. The SBA rules in this section were checked against that SOP text; where lender and law firm blogs word them differently, they're named.
The minimum equity injection for an initial acquisition is 10% of total project cost, and it can't be reduced. Seller debt on standby, other standby debt and minority investor equity share one cap: together they can provide no more than half of that injection.
Half of 10% is 5% of project cost. That's why some write-ups say "50%" and others say "5%". Live Oak Bank, for example, describes a seller note covering "up to 5%" of the requirement.
Full standby doesn't mean the seller gives up interest. The standby debt may accrue interest, which can be added to the note and paid after the 7(a) loan is repaid. Until then, the seller has to subordinate any lien rights to the lender and can't act against you without the lender's consent, usually through SBA Form 155 or the lender's own standby agreement.
Not every seller note has to be on standby. A note that isn't counted as equity can have normal payments, but the lender includes it in your debt service coverage. Other SOP 50 10 8.1 rules that touch the seller note:
- Total debt, including a paying seller note, is capped at the business valuation.
- If a paying seller note is interest-only, the lender has to size it on an amortization of no more than 10 years.
- Debt service coverage must be at least 1.25 for an initial acquisition, up from 1.15 under the previous SOP 50 10 8. It's measured on the last fiscal year or the average of the last two, not on projections (owner-occupied special purpose property is the exception).
- A quality of earnings report is required when the purchase price is $3 million or more, measured before seller debt.
- If you pay more than the business valuation, the difference has to be covered by equity.
- The 7(a) loan can't have a balloon, and the business part can't amortize over more than 10 years.
- The seller can stay on as a consultant for up to 24 months in total.
- A seller who keeps less than 20% of the business must give a full guaranty for the whole loan for at least two years after final disbursement.
Seller earnouts are not allowed in these deals, though buyer rebates based on business performance are. Blake Cantrell, Partner Attorney at Cantrell Law Firm, puts it plainly: "If your deal needs an earnout to bridge a valuation gap, it generally cannot be financed with an SBA loan".
Some older articles and forum threads still say the seller note only has to sit for 24 months. That was the rule under SOP 50 10 7.1 from November 2023, which allowed full or partial standby for the first 24 months. Full standby for the life of the loan started with SOP 50 10 8 in June 2025 and stays in 8.1.
Two buyer stories show the change. Doug Breaker, owner of Shoeboxed, describes splitting his seller financing into a paying note and a standby note with no payments for 24 months. That matches the older rule, and his page says its figures are approximations.
Jimmy Feeman, in a Baton case study on buying Silver Creek Exteriors, asked for 5% of the deal as a separate seller note deferred for 10 years until the SBA loan is paid off. That second shape is what the current rule asks of a standby note.
What does a seller-financed deal look like in numbers?
Take a fictional deal with a total project cost of $1,000,000, a 10-year SBA loan at an assumed 10% rate and a seller note at an assumed 7%. The structure changes how much cash you bring, what you pay each month and how much EBITDA a lender wants to see at 1.25x coverage. The three versions below were calculated with the standard amortization formula and monthly payments.
The 10% SBA rate and the 7% seller rates are assumptions for illustration, not quotes. Put in your lender's rate and the rate you agree with the seller before you rely on any of this.
| A: SBA loan + standby note | B: SBA loan + paying note | C: seller note only | |
|---|---|---|---|
| Your cash | $50,000 | $100,000 | $300,000 |
| Seller note | $50,000 on full standby | $100,000 at 7% over 5 years | $700,000 at 7%, 10-year amortization |
| SBA loan | $900,000 | $800,000 | none |
| Monthly payments | $11,893.57 | $10,572.06 + $1,980.12 | $8,127.59 |
| Debt service per year | $142,722.80 | $150,626.15 | $97,531.12 |
| EBITDA needed at 1.25x | about $178,403 | about $188,283 | no SBA test |
| Balloon | none | none | about $410,460 at year 5 |
In structure A you bring the least cash, and you make no payments on the standby note for 10 years. The seller waits that whole time. If the note accrues interest at an assumed 6%, compounded yearly, the $50,000 grows to about $89,542 by the time the SBA loan is repaid.
Structure B needs twice your cash, and because the seller note pays from day one, it counts in debt service coverage. The lender wants about $188,283 of EBITDA instead of about $178,403. EBITDA here means earnings before interest, taxes, depreciation and amortization, which is the figure SBA lenders divide by debt service.
Structure C skips the bank and has the lowest monthly payment. The catch is the year-5 balloon of about $410,460, which you have to pay or refinance, and a seller who carries 70% of the project cost on their own balance sheet.
How do you ask a seller to finance part of the price?
Ask in a fixed order: price and the valuation behind it first, then the size of the note and how much sits on standby. Rate and term come next, then security, guaranty and default terms, and the seller's role after closing comes last. Put the note's main terms, including any standby, in the letter of intent so they don't come up for the first time when the lender reviews the file.
- Settle the price and how you got there. Know what the business is worth before you size any debt, because in an SBA deal anything you pay above the valuation has to be covered by equity.
- Size the note and split it. Decide which part of the seller note goes on full standby to count toward your injection and which part, if any, pays from day one. Write both into the letter of intent (LOI), the short non-binding document that sets the main terms before diligence.
- Agree on rate and term. Start from the applicable federal rate as the tax floor, and check with your lender before you offer the seller more than the bank's rate.
- Agree on security and any guaranty. Say what the seller gets as collateral, how the UCC-1 is filed and continued, and whether a personal guaranty ends after a set period.
- Write the default terms. Define what counts as default, how long you have to fix it, when the seller can demand the full balance, and your right to set off claims.
- Set the seller's transition role. SBA deals let the seller consult for up to 24 months in total, so agree on what they do and for how long.
It helps to know why a seller says yes or no, and the tax side explains a lot of pushback. A sale with at least one payment after the tax year of the sale is an installment sale for the IRS, reported on Form 6252. The interest the seller earns is generally ordinary income.
Inventory can't be reported on the installment method, and depreciation recapture is taxed in the year of the sale. So a seller can owe tax before the note has paid them anything. Those are questions for the seller's CPA.
Standby is the harder ask. A seller on full standby gets no payments for the whole 7(a) loan term. With a 10-year SBA loan, as in Structure A of the $1M example, that means 10 years. If you found the business by approaching the owner before a listing exists, there may be no broker in the middle, so you'll explain this to the owner yourself.
What can go wrong after closing?
Most problems after closing come from cash flow, paperwork or the old owner leaving. If revenue drops, you can fall behind on the note, and the seller can call a default and act on any security. A seller on full standby waits for the whole SBA loan term, and a UCC-1 that nobody continues lapses after five years. And if clients follow the old owner out, the money for the note leaves with them.
Default is where the note's wording matters most. Outside the SBA, the seller's options depend on the default and acceleration clauses you signed. With an SBA loan in the deal, a standby seller can't take action against you or the collateral without the lender's consent.
Paperwork fails quietly. A filed UCC-1 is effective for five years, and a continuation can only be filed in the last six months before it expires. On a 7- or 10-year note, someone has to put that date in a calendar. Refinancing is slow too: to refinance a seller note with an SBA loan, it must have been in place and current, not on standby, for at least 36 months.
The last risk is the owner. If clients buy because of the person who runs the company, and that person is leaving, your pipeline may leave too. A business with revenue that depends on the owner can lose clients when the owner steps back, and your note payments come out of the same cash. In diligence, ask who holds the top client relationships, how much revenue sits with the largest clients, and who closed the last ten deals.
At Chrysales, we'd treat the handover of client relationships as part of the deal itself. Use the seller's consulting period for introductions, and start setting up revenue operations that don't depend on one person in the first months, while the seller is still around.
Checklist before you sign
Three people should read the deal before you sign: a lawyer for the note and security documents, a CPA for the tax side on both ends, and your lender for the SBA rules. Go through this list with all three and settle any open points before you sign.
- The price is backed by a valuation, and any amount above it is covered by equity.
- Your injection is at least 10% of total project cost, and no more than half of it comes from standby and other limited sources.
- Any seller note counted as equity is subordinated and on full standby for the whole 7(a) loan term, with a signed SBA Form 155 or the lender's equivalent.
- Your historical EBITDA covers all debt service, including any paying seller note, at least 1.25 times.
- The note's rate is at or above the applicable federal rate for the month of the sale.
- The note states term, payment schedule, balloon if any, prepayment, default, cure period and acceleration.
- Security is described, the UCC-1 continuation date is in a calendar, and any personal guaranty has a clear end.
- There's no earnout if an SBA loan is involved, and the seller's consulting role stays within 24 months.
- You know who holds the main client relationships and how they'll be introduced to you.
FAQ
Can you buy a business with no money down using seller financing?
Don't plan on it. For an SBA 7(a) initial acquisition, the equity injection is at least 10% of project cost, and a standby seller note can cover no more than half of it. Without an SBA loan, the down payment is whatever you and the seller agree, and Surge Business Law puts the usual range at 10% to 50% of the price.
Can the seller note be the down payment for an SBA loan?
Part of it can. Under SOP 50 10 8.1, a seller note counts as equity only if it's subordinated to the lender and on full standby for the whole loan term. Together with other limited sources it can cover at most half of the required 10% injection, which is 5% of project cost.
What interest rate is normal on a seller note?
There's no official benchmark. Surge Business Law says seller financing rates typically range from 5% to 8%, while an SBA lender on searchfunder sees 5% to 6%, with 7% to 8% as a maximum. The rate shouldn't fall below the IRS applicable federal rate for the month of the sale, which was 4.61% mid-term in October 2026.
What happens if the buyer defaults on a seller note?
It depends on the note. For a note without SBA standby, the seller's options are the default and acceleration clauses in the note and any collateral that was properly filed. If the note is on SBA standby, the seller has to subordinate lien rights and can't take action without the lender's consent.
Is owner financing a good idea for the seller?
It can be, with conditions. The seller earns interest, which the IRS generally treats as ordinary income, and reports the sale as an installment sale on Form 6252. The risks are a buyer who defaults, depreciation recapture taxed in the year of sale, and, in SBA deals, a standby note that pays nothing until the 7(a) loan is repaid.
Sources
- SBA - SOP 50 10: Lender and Development Company Loan Programs (SOP 50 10 8.1, Appendix 15)
- SBA Information Notice 5000-880695 - Issuance of SOP 50 10 8.1 (copy hosted by Coleman Report)
- IRS - Topic no. 705, Installment sales
- IRS - Publication 537, Installment Sales
- IRS - Rev. Rul. 2026-19, applicable federal rates for October 2026
- Cornell Law School LII - UCC 9-515, duration of a financing statement
- IBBA and M&A Source - Market Pulse Q2 2026 highlights
- IBBA Q2 2026 Market Pulse release (via Webull)
- Surge Business Law - Seller Financing When Buying a Business: How It Works
- searchfunder - How to Structure Seller Financing the Right Way
- Live Oak Bank - SBA SOP 50 10 8: Key 2025 Updates and What's New
- Cantrell Law Firm - Selling Your Business? The SBA Just Changed the Math
- SEC - ONAR Holding Corporation Form 8-K
- Baton - How a Franchise Founder Bought a Cash-Flowing Construction Business (Jimmy Feeman, Silver Creek Exteriors)
- Shoeboxed - SBA Loan Down Payment: How I Bought a $1M+ Business for 5% Down (And A Warning)
Buying a company whose clients still call the old owner? A free strategy call with Chrysales is a place to talk through the client acquisition system that business needs, so the pipeline doesn't depend on the seller's relationships. Plan the sales handover for your acquisition on a free call
Scaling Is Not Hard If You Have The Right Systems
If you’re serious about leveling up your scaling game, you need the right system, the right training, and the right team behind you. We're here to give you the exact tools and strategies top entrepreneurs use to dominate.
Discover the latest tips
View All
Chrysales was formed from the words "chrysalis" the stage where a caterpillar transforms into a butterfly and "sales".
It stands for one thing: sales transformation.Because scaling doesn’t happen by doing more of the same. Scaling only happens when you go through real transformation in your systems, your offer, team and the way you sell.


